

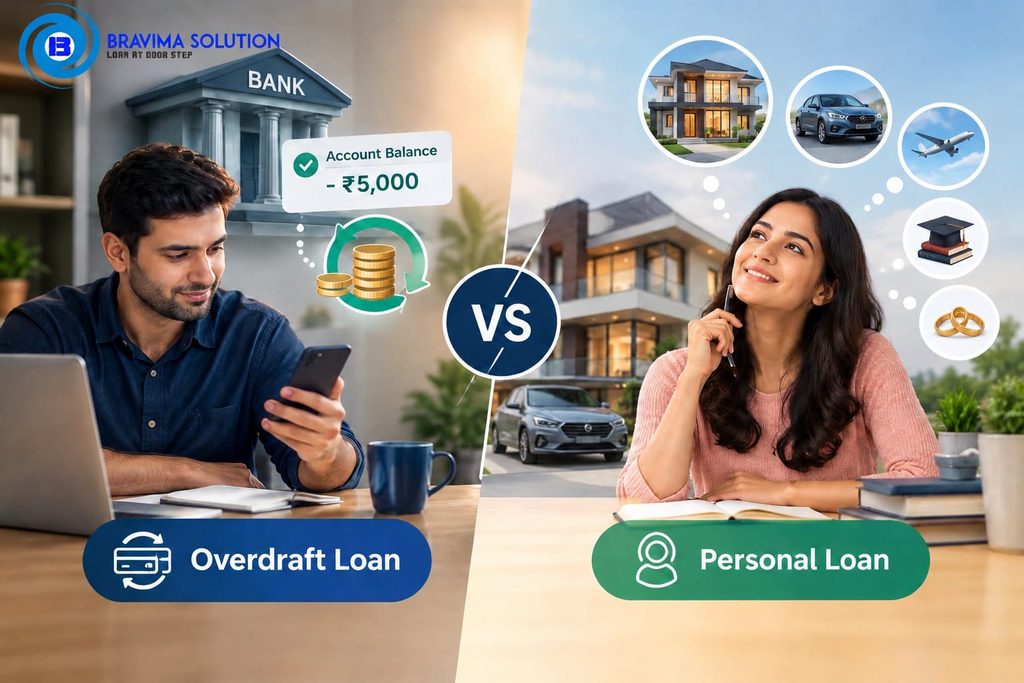
An Overdraft (OD) limit and a Personal Loan are both credit facilities, but they function very differently in terms of interest calculation, repayment flexibility, and cost efficiency. When evaluating funding options for your upcoming financial needs, choosing the right credit structure can make a significant difference in your overall borrowing costs and cash flow management.
While a Personal Loan offers a fixed lump-sum amount repaid via monthly EMIs, an Overdraft (OD) Limit acts as a flexible, revolving line of credit designed to optimize interest expenses.
Key Factors:Overdraft Limit vs. Personal Loan
| Feature / Factor | Overdraft (OD) Limit | Personal Loan |
|---|---|---|
| Interest Calculation | Charged only on the utilized amount for the exact number of days used. | Charged on the entire sanctioned loan amount from Day 1. |
| Repayment Structure | Flexible; pay back any amount, anytime. Principal lowers instantly upon deposit. | Fixed monthly EMIs (Principal + Interest) over a fixed tenure. |
| Prepayment/Foreclosure Charges | Typically Nil; deposit funds back without penalty. | Often attracts foreclosure/prepayment fees (usually 2%–5%). |
| Re-usability of Funds | Re-usable like a revolving line of credit within the approved tenure. | One-time disbursal. Reborrowing requires a top-up loan application. |
| Best Used For | Short-term cash flow gaps, business needs, unpredictable expenses. | Planned, large, one-time fixed expenses (e.g., home renovation, weddings). |
Key Benefits of an Overdraft Limit over a Personal Loan
Pay Interest Only on What You Use
- If you have an OD limit of ₹5,000,000 but only withdraw ₹1,000,000 for 10 days, you pay interest only on ₹1,000,000 for those 10 days. But with a personal loan, you would pay interest on the full ₹5,000,000 from day one.
Pay Interest Only on What You Use – Get an Overdraft Limit Today!
Deposit Idle Surplus & Save Interest
Any money deposited into an OD account reduces the outstanding balance immediately, lowering your daily interest burden. In a personal loan:
- Firstly, it will not be allowed by any bank.
- If allowed, then again 3% – 4% charges would attract on the part-paid amount.
No Lock-in EMI Burden
- Unlike personal loans with rigid EMIs, an OD facility gives you the freedom to pay down the balance whenever funds are available.
Revolving Credit Line
- You don’t need to re-apply every time you need extra cash; funds are readily available up to your sanctioned limit.
Tired of Fixed EMIs? Switch to a Flexible Overdraft Limit!
Interest on Utilization Only
Unlike a Personal Loan where interest applies to the total sanctioned amount from Day 1, an OD facility charges interest strictly on the amount you actually withdraw, for the exact number of days used.
Smart Interest Savings
Whenever you have surplus funds, you can deposit them into your OD account. This immediately reduces your outstanding principal balance and lowers your daily interest calculation.
No Rigid EMI Obligations
You enjoy the flexibility to repay principal amounts whenever your cash flow allows, eliminating the stress of fixed monthly instalments during quiet business/financial cycles.
Re-usable Credit Line
As you repay the utilized amount, your available limit restores automatically, allowing you to draw funds repeatedly without going through repeated loan application processes.
Zero Prepayment Penalties
You can clear your utilized balance at any time without incurring foreclosure or prepayment penalty charges typically associated with fixed Personal Loans.
Save More on Interest – Apply for Your Overdraft Limit Now!
Which option is right for you?
Choose an Overdraft Limit if you require funds for unpredictable cash flow needs, emergency fund needs, ongoing expenses, or short-term liquidity, giving you complete control over your interest outflow.
Choose a Personal Loan if you require a one-time fixed payout with a fixed repayment timeline.
We would be happy to evaluate your requirements and structure an Overdraft facility tailored to your needs. Please let us know a suitable time to connect.
- Overdraft Limit vs Personal Loan: How You Save More on Interest & Get Full Repayment FreedomAn Overdraft (OD) limit and a Personal Loan are both credit facilities, but they function very differently in terms of… Read more: Overdraft Limit vs Personal Loan: How You Save More on Interest & Get Full Repayment Freedom
- Rebuilding Credit After Bad Debt: A Complete Guide to Improve Your CIBIL Score
 Falling into bad debt can feel overwhelming, but it doesn’t have to define your financial future. Whether you’ve missed EMI… Read more: Rebuilding Credit After Bad Debt: A Complete Guide to Improve Your CIBIL Score
- Which is better Term Loans vs Overdraft Loans
 Businesses often need external financing to manage cash flow, purchase equipment, expand operations, or handle unexpected expenses. Two of the… Read more: Which is better Term Loans vs Overdraft Loans
- Best Personal Loan in Gurugram: Compare Top Banks, Rates & Instant Approval
 Gurugram, known as the Millennium City, is a hub of professionals, entrepreneurs, and fast-paced lifestyles. Whether it’s for a medical… Read more: Best Personal Loan in Gurugram: Compare Top Banks, Rates & Instant Approval
- Best Overdraft Loan Provider in Delhi NCR – Instant OD Loan Approval for Salaried
 Looking for an instant overdraft loan in Delhi NCR? Bravima Solution helps salaried employees, self-employed professionals, freelancers, and business owners… Read more: Best Overdraft Loan Provider in Delhi NCR – Instant OD Loan Approval for Salaried
- Poonawalla Fincorp Personal Loan – Get ₹50 Lakh at 9.99% Interest
 In today’s fast-paced world, financial needs can arise anytime—whether it’s for medical emergencies, weddings, travel, or debt consolidation. If you… Read more: Poonawalla Fincorp Personal Loan – Get ₹50 Lakh at 9.99% Interest
