

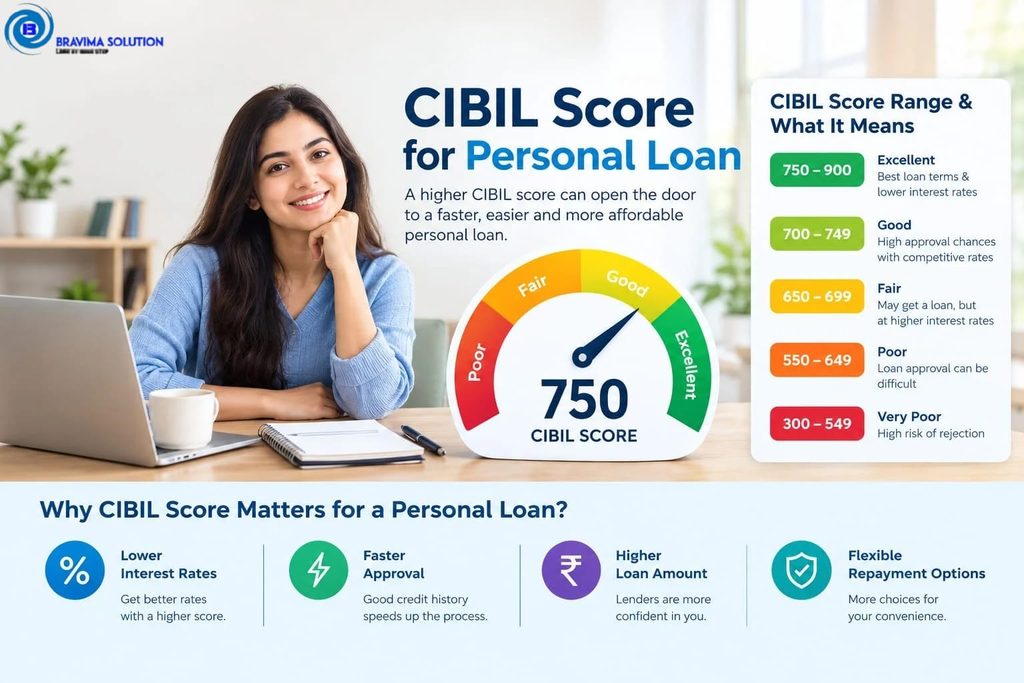
Your CIBIL score for a personal loan plays the biggest role in whether lenders approve your application and what interest rate they offer you. A low score can mean rejection or higher interest, while a strong score opens doors to the best deals from NBFCs and banks. In this guide, we break down the minimum CIBIL score required, how it impacts your loan, and simple ways to improve it before you apply.
What Is a CIBIL Score?
A CIBIL score is a three-digit number ranging from 300 to 900 that represents your creditworthiness. It is calculated based on your repayment history, credit utilization, credit mix, and number of credit inquiries. Lenders use this score to decide whether to approve your personal loan and at what interest rate.
Minimum CIBIL Score Required for a Personal Loan
| CIBIL Score Range | Loan Approval Chances | Interest Rate Impact |
|---|---|---|
| 750 – 900 | Excellent — High approval chances | Lowest interest rates offered |
| 700 – 749 | Good — Most lenders approve | Competitive interest rates |
| 650 – 699 | Fair — Approval possible with NBFCs | Higher interest rates |
| Below 650 | Low — Limited options, may need a co-applicant | Highest interest rates or rejection |
At Bravima Solution Pvt Ltd, we help applicants across all score ranges find the right NBFC or bank for their personal loan needs.
How CIBIL Score Affects Your Personal Loan
1.Loan Approval
Most banks and NBFCs prefer a CIBIL score of 700 or above for quick approval. A low score increases the risk of rejection or demands for additional documentation.
2.Interest Rate
A higher score can help you negotiate lower interest rates, saving you thousands over the loan tenure. A low score often means higher EMIs for the same loan amount.
3.Loan Amount Eligibility
Lenders may sanction a lower loan amount if your score is below their threshold, even if your income supports a higher amount.
4.Processing Speed
Applicants with strong scores often get instant or same-day approval, especially through NBFCs like Bajaj Finserv and Tata Capital.
How to Improve Your CIBIL Score Before Applying
- Pay EMIs and credit card bills on time — Payment history is the biggest factor in your score.
- Keep credit utilization below 30% — Avoid maxing out your credit cards.
- Avoid multiple loan applications in a short time — Each inquiry can slightly lower your score.
- Check your credit report for errors — Dispute any incorrect entries that may be pulling your score down.
- Maintain a healthy credit mix — A mix of secured and unsecured credit helps your profile.
- Don’t close old credit accounts — A longer credit history works in your favor.
These small steps, followed consistently for 3-6 months, can meaningfully improve your score and your loan eligibility.
What If Your CIBIL Score Is Low?
Even with a lower CIBIL score, you may still qualify for a personal loan through:
- NBFCs that evaluate income and employment stability alongside credit score
- Adding a co-applicant with a strong credit profile
- Offering collateral to reduce lender risk
- Opting for a smaller loan amount to improve approval odds
At Bravima Solution, we match applicants with lenders most likely to approve based on their complete financial profile — not just the CIBIL score alone.
Frequently Asked Questions
What is the minimum CIBIL score for a personal loan?
Most banks prefer a CIBIL score of 700 or above, while NBFCs may approve loans for scores as low as 650, often at higher interest rates.
Can I get a personal loan with a CIBIL score below 600?
It’s difficult but not impossible. You may need a co-applicant, collateral, or need to approach NBFCs that specialize in lower-score applicants.
How long does it take to improve a CIBIL score?
With consistent on-time payments and low credit utilization, noticeable improvement can take 3-6 months, though significant changes may take longer.
Does checking my CIBIL score lower it?
No. Checking your own score is a “soft inquiry” and does not affect your CIBIL score. Only lender-initiated “hard inquiries” during loan applications have a small impact
Which lenders offer personal loans for average CIBIL scores?
NBFCs like Bajaj Finserv, Tata Capital, and Fullerton India are generally more flexible with average credit scores compared to traditional banks.
Related Article
Your Main Post Content
Yahan apni main post ka content rakhein.
